The ideal amount for a Roth conversion before Medicare IRMAA is the maximum sum that keeps your income below the next surcharge threshold while staying within your target tax bracket. Exceeding these income cliffs is generally considered too much because it triggers higher Medicare premiums through a two year lookback period, although minor surcharges may be acceptable if they drastically reduce future required minimum distributions.
Many retirees view Roth conversions as the ultimate tool for long term tax efficiency; yet, a poorly timed transfer can trigger a hidden tax in the form of higher Medicare premiums. This surcharge, known as IRMAA, often catches high earners by surprise because of the federal government’s two year lookback period. If you convert too much, you might save on future income taxes only to lose those gains to inflated Part B and Part D costs. Understanding where the cliff lies is essential for protecting your cash flow during your golden years. In this guide, we examine the critical intersection of tax strategy and healthcare costs. You will learn how to navigate the 2026 IRMAA brackets, identify the ideal gap years for conversions, and calculate exactly how much you can move into a Roth account without triggering a costly premium hike.
The Intersection of Tax Strategy and Medicare Premiums
A Roth conversion is a powerful wealth preservation tool that allows you to pay taxes today in exchange for tax-free growth and distributions in the future. For many Gilbert families, this serves as a cornerstone of a tax-smart income strategy. However, executing a Roth conversion before Medicare IRMAA surcharges are accounted for can lead to a costly surprise. While most retirees focus intently on federal income tax brackets, they often overlook the hidden cliff of Medicare premiums.
The Income-Related Monthly Adjustment Amount, or IRMAA, is an additional surcharge added to Medicare Part B and Part D premiums for higher-income earners. Because the Social Security Administration uses a two-year lookback period to determine these costs, a conversion performed today could spike your healthcare expenses two years down the road. This creates a unique intersection where tax planning and healthcare planning must align. Simply staying within a specific tax bracket is not enough; you must also calculate how that extra income affects your future Medicare eligibility. Timing is the critical factor in preserving dependable retirement income while minimizing the total cost of your transition into tax-free wealth. Understanding this interplay is essential to avoid the sticker shock of premium hikes that many retirees fail to see coming.
The Two Year Lookback Rule for Medicare Premiums
The connection between your current tax return and your future healthcare costs is defined by the Social Security Administration’s lookback period. Many retirees mistakenly believe that their current monthly income determines their Medicare premiums. In reality, the Social Security Administration (SSA) reviews your modified adjusted gross income (MAGI) from your tax return filed two years prior. This means that a strategic decision to perform a Roth conversion in 2024 directly dictates your Medicare Part B and Part D costs in 2026. This 2 year rule creates a lag that can catch even the most diligent planners off guard if they only focus on the immediate tax year.
This timeline is particularly critical for those approaching age 65. Because of the lookback, your financial activity at age 63 sets the stage for your initial Medicare enrollment costs. If you execute a large Roth conversion at 63 to reduce future Required Minimum Distributions (RMDs), you must account for the reality that those funds will be factored into your premium calculation the moment you sign up for Medicare. This administrative delay makes it essential to view retirement income planning through a long-term lens, ensuring that actions taken today do not negatively impact your dependable retirement income later.
Confusion often arises because the IRS and SSA operate on different schedules. While you pay the income tax on a conversion when you file your return for that year, the IRMAA surcharge does not arrive until two calendar years later. For individuals in Gilbert, failing to account for this delay can result in an unexpected spike in monthly expenses just as they are settling into their retirement routine. Proactive planning must occur well before you reach the next age tier or enroll in Part B to ensure your tax-smart income strategy remains efficient over the long haul.
Understanding the 2026 IRMAA Brackets and the Cliff Effect
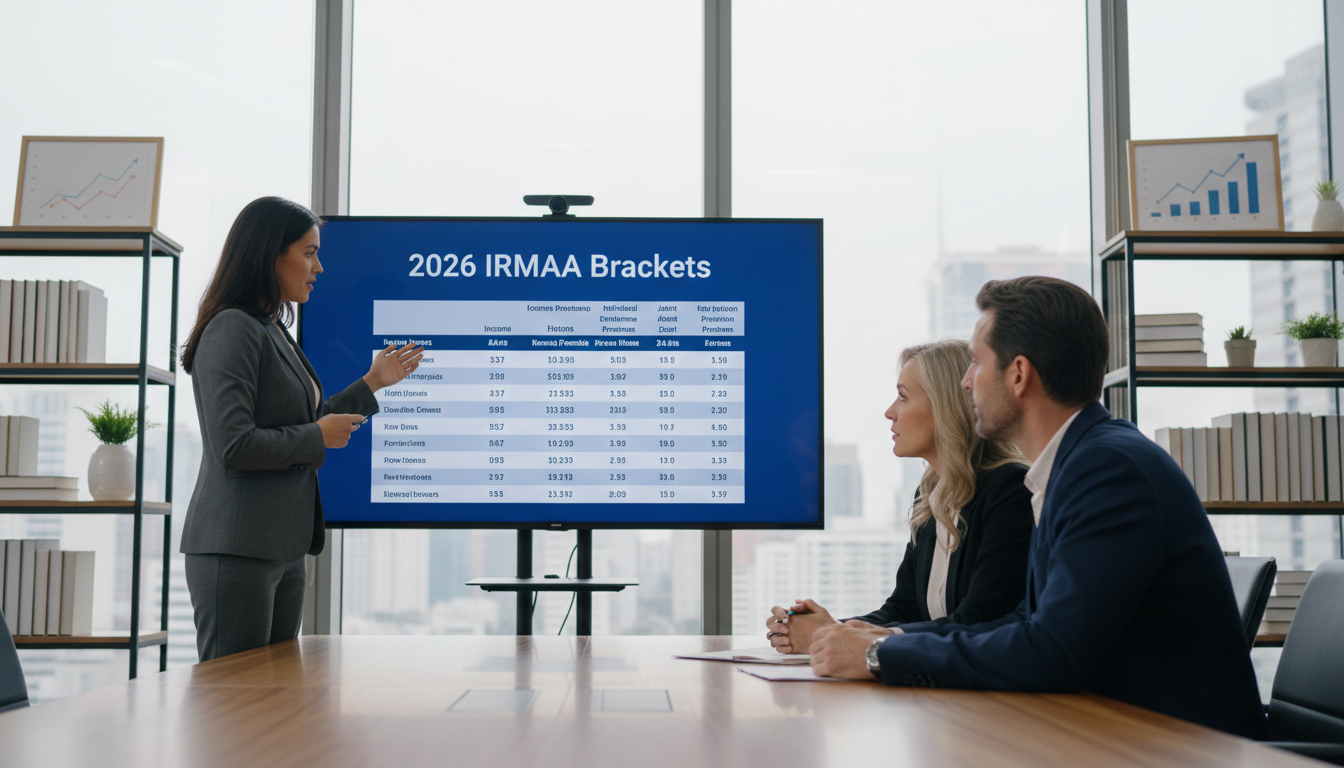
Building on the mechanics of the lookback period, it is essential to understand the specific financial boundaries that trigger these surcharges. IRMAA, or the Income-Related Monthly Adjustment Amount, is an added cost for Medicare Part B (medical insurance) and Medicare Part D (prescription drug coverage). It is not a tax in the traditional sense, but rather a reduction in the federal subsidy of your healthcare premiums. For the 2026 calendar year, the Social Security Administration will look at your 2024 tax return to see if you exceed the base thresholds. Based on recent projections, these thresholds are set at $109,000 for single filers and $218,000 for those married filing jointly.
The defining characteristic of these surcharges is the "Cliff Effect." Most retirees are accustomed to the progressive nature of federal income tax brackets, where moving into a higher bracket only results in a higher rate being applied to the dollars that fall within that specific range. IRMAA does not operate this way; it is a series of hard cliffs. If your modified adjusted gross income (MAGI) is even one dollar over the threshold, you are triggered into the next tier for the entire year. This results in the full surcharge being applied to your monthly premiums, regardless of how small the overage was.
2026 Filing Status (Based on 2024 Income) | MAGI Threshold | Part B Monthly Surcharge | Part D Monthly Surcharge |
|---|---|---|---|
Single | $109,000 or less | $0.00 | $0.00 |
Single | $109,001 to $136,000 | $81.10 (est.) | $14.50 |
Married Joint | $218,000 or less | $0.00 | $0.00 |
Married Joint | $218,001 to $272,000 | $81.10 (est.) | $14.50 |
For a married couple in Gilbert, both individuals are subject to the surcharge once the household passes the $218,000 mark. If a Roth conversion accidentally pushes a couple to $218,001, the combined cost increase for Part B and Part D could exceed $2,294 for the year. This sudden spike can erode the benefits of a tax-smart income strategy if not managed precisely. To protect your dependable retirement income, you must treat these thresholds as hard ceilings when calculating the size of your annual conversion.
How to Calculate Your Maximum Roth Conversion Without Triggering IRMAA
To avoid falling off the "cliff" described above, you must determine your precise conversion runway. This is the gap between your existing income and the next IRMAA threshold. Calculating this requires shifting focus from standard taxable income to Modified Adjusted Gross Income (MAGI) as specifically defined by the Social Security Administration for Medicare purposes.
Follow this step-by-step formula to estimate your maximum conversion for the tax year:
Identify the relevant IRMAA threshold for your filing status. For the 2026 premium year (based on 2024 income), use $109,000 for single filers or $218,000 for joint filers.
Total your projected income sources, including Social Security benefits, pension payments, required distributions, dividends, and wages.
Add back tax-exempt interest. A common oversight in a tax-smart income strategy is forgetting that municipal bond interest, while tax-free for the IRS, is added back to your MAGI for IRMAA calculations.
Subtract your total projected MAGI from the IRMAA threshold identified in step one.
The resulting figure is the maximum amount you can move into a Roth account without triggering a surcharge. For example, a married couple in Gilbert with $165,000 in projected MAGI (including their muni bond interest) has a conversion runway of $53,000 before they hit the first IRMAA tier.
Precise calculation is vital because even a small oversight can disrupt your dependable retirement income by adding thousands in annual premiums. Properly timing a Roth conversion before Medicare IRMAA thresholds are breached ensures you capture the benefits of tax-free growth without incurring the unnecessary cost of higher healthcare premiums.
The Golden Window: The Gap Years Strategy
Successful retirement income planning often hinges on identifying the "gap years," the strategic window between your final paycheck and the commencement of Social Security or Required Minimum Distributions (RMDs). For a Gilbert professional retiring at age 60, this period offers a unique environment where taxable income is often at its lowest point. During these years, you can shift assets from a traditional IRA to a Roth IRA at historically low tax rates. Because the Medicare lookback does not impact you until age 63, you can perform a larger Roth conversion before Medicare IRMAA thresholds even become a concern.
Reducing the balance of your pre-tax accounts now serves a dual purpose. It lowers the principal amount used to calculate future RMDs, which start at age 73 for those born between 1951 and 1959, and age 75 for those born in 1960 or later. By shrinking these future mandatory withdrawals, you proactively protect yourself against the IRMAA cliff during your 70s and 80s. This level of foresight is a hallmark of a tax-smart income strategy, ensuring your dependable retirement income remains insulated from rising healthcare surcharges. Focusing on this window allows you to pay taxes on your own terms rather than the government's.
Is Paying the IRMAA Surcharge Ever Worth It?
Retirees often view IRMAA as a penalty to be avoided at all costs, yet a strict avoidance strategy can sometimes be penny wise and pound foolish. When evaluating a Roth conversion before Medicare IRMAA surcharges are triggered, you must weigh a one year premium increase against decades of tax free compounding. For instance, a single filer who crosses into the first IRMAA tier may face approximately $1,147 in additional annual premiums. While this sticker shock is real, it is often a small price to pay if a larger conversion prevents much larger tax liabilities down the road.
Consider a scenario where a Gilbert resident converts an additional $100,000. This move might trigger a one year IRMAA surcharge, but it removes that $100,000 from a traditional IRA where it would eventually be subject to RMDs. Over fifteen years, assuming a 6% growth rate, that account would have grown to roughly $240,000. By paying the IRMAA surcharge today, the retiree protects that entire future balance from income tax. This proactive approach is a hallmark of a tax-smart income strategy. Instead of focusing solely on the immediate cost, successful planners look at the net wealth preserved. Reducing the total size of tax deferred accounts can stabilize your dependable retirement income for the long term, even if it requires navigating a temporary premium hike.
Retirement Planning Nuances for Gilbert Residents
While Medicare rules are federal, your local financial environment in Gilbert significantly influences the math behind a Roth conversion before Medicare IRMAA surcharges are calculated. Arizona offers favorable tax treatment, including the full exemption of Social Security benefits from state income tax and specific exclusions for certain pension incomes. These local tax breaks can lower your overall state tax liability, providing more liquidity to cover the upfront costs of a tax-smart income strategy.
However, the relatively higher cost of living in Gilbert often necessitates larger monthly withdrawals to sustain your lifestyle. This increased cash flow requirement must be carefully balanced against federal IRMAA thresholds to avoid accidental cliff triggers. Integrating these local nuances with federal regulations is vital to ensuring your dependable retirement income remains robust and predictable throughout your retirement.