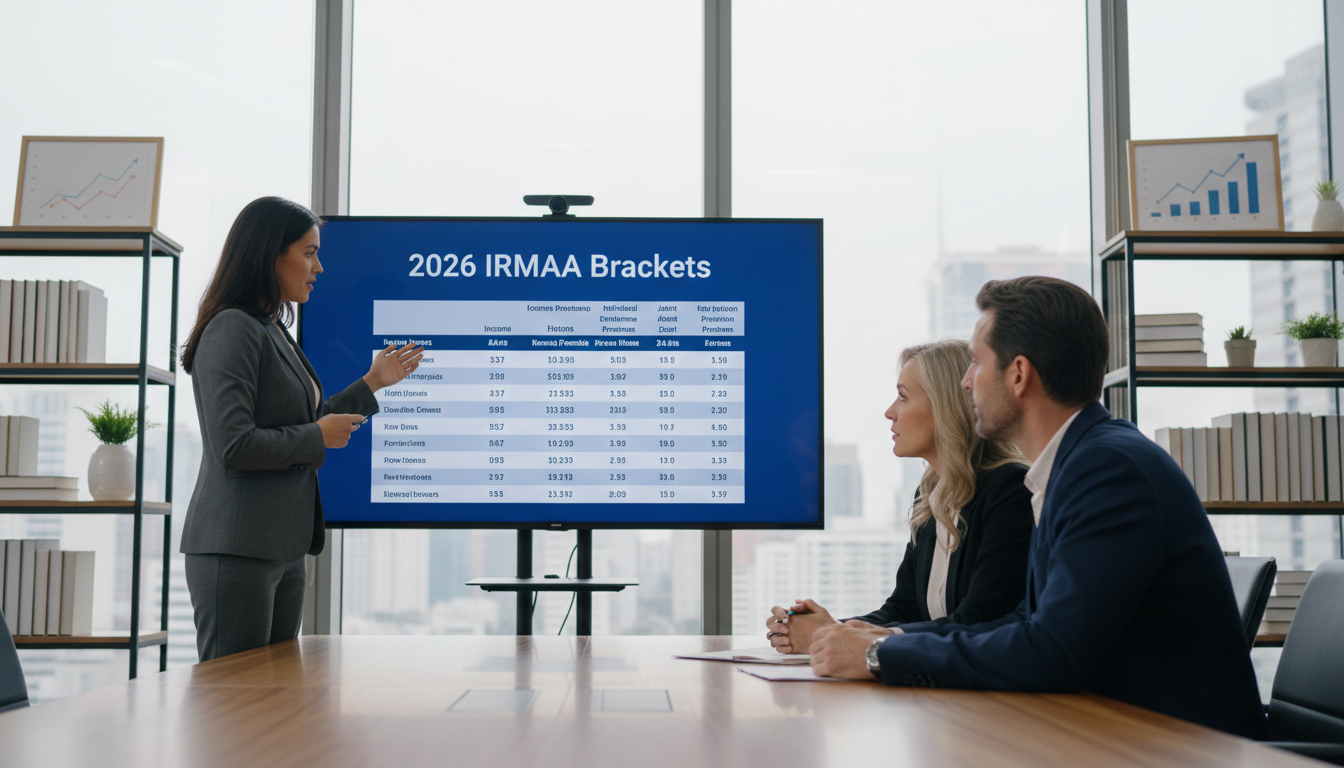
The 2026 IRMAA brackets set income thresholds starting at $109,000 for single filers and $218,000 for joint filers, which determine additional Medicare Part B and Part D surcharges. These surcharges range from approximately $1,148 to $6,936 per person based on tax returns from the 2024 lookback year. Retirees can potentially avoid these higher costs by using strategies such as Roth conversions, income timing, or qualified charitable distributions.
For many high net worth retirees, the realization that Medicare premiums are not a flat rate comes as a costly surprise. The Income Related Monthly Adjustment Amount, or IRMAA, acts as a progressive surcharge that can significantly erode your retirement distributions if left unmanaged. Because the Social Security Administration utilizes a two year lookback period, the financial decisions you make today are already setting the stage for your 2026 obligations. Understanding these thresholds is essential for preserving your capital and maintaining long term tax efficiency. In this guide, we will analyze the projected 2026 IRMAA brackets for both single and joint filers. You will learn how specific income triggers like capital gains and Required Minimum Distributions impact your status, and we will explore sophisticated strategies, including Roth conversions and Qualified Charitable Distributions, to mitigate these surcharges before they take effect.
Understanding the 2026 IRMAA Brackets and the Two Year Lookback Rule
Medicare is often viewed as a fixed cost in retirement, but for many households in Gilbert, the actual price of coverage depends heavily on annual income. This variable cost is known as the Income Related Monthly Adjustment Amount, or IRMAA. Rather than a separate tax, IRMAA functions as a mandatory surcharge added to your standard Medicare Part B and Part D premiums. If your income exceeds specific thresholds, you effectively lose a portion of the federal subsidy that typically offsets Medicare costs, resulting in significantly higher monthly bills.
The most critical aspect of navigating the 2026 IRMAA brackets is understanding the two year lookback rule. The Social Security Administration determines your 2026 premiums by reviewing your 2024 federal tax return. This delay creates a significant planning gap. Many retirees do not realize that a high income year in 2024, perhaps from a property sale or a large IRA withdrawal, will not trigger a surcharge until 2026. This means the window to influence your 2026 healthcare costs is open right now.
Because of this mechanism, effective retirement planning must happen well in advance. Decisions made today regarding your tax-smart income strategy determine your healthcare expenses two years down the road. If you wait until you receive a notice in the mail to address these surcharges, you have already missed the window to mitigate the impact. For residents in the Gilbert area, proactive management of Modified Adjusted Gross Income (MAGI) during 2024 is the only way to maintain control over the 2026 Medicare surcharges.
Projected 2026 IRMAA Income Thresholds for Single and Joint Filers
The thresholds for the 2026 IRMAA brackets are determined by your tax filing status and your modified adjusted gross income (MAGI) from 2024. For individuals, the surcharges begin when income exceeds $109,000. For couples filing a joint return, that threshold is $218,000. It is vital to understand that IRMAA operates differently than the progressive federal income tax system. In a standard tax bracket, you only pay the higher rate on the dollars that fall into that specific bracket. IRMAA, however, functions as a cliff. If your income is just one dollar over the threshold, you are responsible for the entire monthly surcharge for the full year.
To help visualize the financial impact, consider the five surcharge tiers below. These represent the additional costs added to the projected standard Part B premium of $202.90.
Tier | Single Income (2024) | Joint Income (2024) | Monthly Part B Surcharge | Monthly Part D Surcharge |
|---|---|---|---|---|
Tier 1 | $109,001 – $136,000 | $218,001 – $272,000 | $81.20 | $14.50 |
Tier 2 | $136,001 – $170,000 | $272,001 – $340,000 | $202.90 | $37.50 |
Tier 3 | $170,001 – $204,000 | $340,001 – $408,000 | $324.60 | $60.40 |
Tier 4 | $204,001 – $499,999 | $408,001 – $749,999 | $446.30 | $83.30 |
Tier 5 | ≥ $500,000 | ≥ $750,000 | $487.00 | $91.00 |
For high-earning households, these adjustments are substantial. A retiree in the highest tier could see their monthly Part B cost rise to $689.90. When combined with the Part D surcharge, a couple could pay thousands of dollars in extra premiums annually simply because their income slightly crossed a tier boundary. This is why obtaining a personalized retirement analysis is such a crucial part of our process. By identifying exactly where your 2024 income falls relative to these tiers, we can help you implement strategies to stay below the cliff and preserve your retirement cash flow.
What Types of Income Trigger the Medicare Surcharge
To successfully navigate the 2026 IRMAA brackets, you must first understand the specific formula the Social Security Administration uses to calculate your Modified Adjusted Gross Income (MAGI). For Medicare purposes, MAGI is your Adjusted Gross Income (AGI) plus any tax-exempt interest income. This inclusion of tax-exempt interest is a frequent point of confusion for retirees in Gilbert who utilize municipal bonds as part of their portfolio. While that interest avoids federal income tax, it is fully counted when determining your Medicare premium surcharges.
The primary income sources that build this total include: - Taxable and tax-exempt interest (including municipal bonds). - Ordinary and qualified dividends. - Capital gains from the sale of securities or real estate. - The taxable portion of Social Security benefits. - Monthly pension payments. - Distributions from traditional IRAs and 401(k) accounts, including Required Minimum Distributions (RMDs).
Because IRMAA is based on the combined total of these streams, retirees often experience an "income stack" effect. A household with a well-structured lifetime income strategy might still be pushed into a higher bracket by a single event, such as a large RMD or the sale of a highly appreciated asset. Since even one dollar over the threshold triggers the full surcharge, it is vital to track how these various income sources interact throughout the tax year.
Strategic Roth Conversions to Lower Future MAGI
Strategic Roth conversions represent a primary defense against the long term impact of the 2026 IRMAA brackets. By moving funds from a tax deferred traditional IRA to a tax free Roth IRA, you are essentially making a trade. You agree to pay taxes on the converted amount today in exchange for a lifetime income strategy that is free from both income tax and the Medicare surcharge calculation in the future.
While a Roth conversion increases your MAGI in the year it is performed, it effectively shrinks the pool of assets subject to future Required Minimum Distributions (RMDs). Because RMDs are often the largest single driver of high MAGI for retirees, reducing them can permanently lower your income profile in later years. For example, a significant conversion in 2024 might push you into a higher IRMAA tier for your 2026 premiums, but this short term surcharge can be far outweighed by the long term savings of staying in a lower bracket for the next two decades.
To manage this transition effectively, we often recommend a bracket topping strategy. This involves calculating exactly how much room you have left in your current income or IRMAA tier and converting only enough to reach that threshold without crossing it. By staying disciplined with these incremental conversions, you can gradually shift your wealth into a tax free environment without triggering an unnecessary cliff. A personalized retirement analysis is essential here, as it allows you to visualize how these conversions interact with other income sources. This proactive approach ensures your tax-smart income strategy balances today’s tax costs with tomorrow’s Medicare efficiency.
Utilizing Qualified Charitable Distributions (QCDs) for RMD Management
While Roth conversions manage future income, Qualified Charitable Distributions (QCDs) provide an immediate way to lower MAGI today. For individuals aged 70.5 or older, a QCD allows for the direct transfer of up to $105,000 per year from a traditional IRA to a qualified charity. Unlike a standard withdrawal that is first recognized as income and then potentially deducted, a QCD is never included in your Adjusted Gross Income to begin with. This distinction is vital for maintaining a tax-smart income strategy.
Because the 2026 IRMAA brackets are sensitive to every dollar of MAGI, using a QCD to satisfy some or all of your Required Minimum Distribution (RMD) can be the difference between staying in a lower tier and hitting a surcharge cliff. If you are already charitably inclined, this strategy allows you to support causes you care about while keeping your reported income below the thresholds for higher Medicare premiums. For many in Gilbert, this is an underutilized tool. Even if you do not itemize deductions on your tax return, you still receive the full benefit because the income is simply excluded. When we perform a personalized retirement analysis, we often identify opportunities to replace taxable RMDs with QCDs. This proactive management is a sophisticated way to refine your lifetime income strategy without sacrificing your philanthropic goals.
The Widow and Widower Trap: Why IRMAA Planning Changes After a Spouse Passes
One of the most overlooked risks in retirement is the sharp transition from Married Filing Jointly to Single status following the death of a spouse. Often called the survivor’s trap, this shift significantly alters how a household interacts with the 2026 IRMAA brackets. While a couple might comfortably stay below the projected $218,000 joint threshold, a surviving spouse suddenly faces a much lower individual threshold of $109,000.
The financial challenge arises because household income rarely drops by half when a spouse passes. A survivor typically retains the higher of the two Social Security payments and often receives survivor benefits from a pension. Furthermore, Required Minimum Distributions (RMDs) from the deceased spouse's retirement accounts generally continue, now concentrated on a single tax return. This combination frequently pushes the survivor into a higher Medicare tier, triggering steep surcharges on a single income. Because IRMAA is a cliff, being just slightly over the $109,000 limit results in the full surcharge for both Part B and Part D.
Proactive legacy planning addresses this vulnerability before it happens. Through a personalized retirement analysis, we model how a change in filing status impacts future Medicare costs. Incorporating a tax-smart income strategy that emphasizes Roth conversions while both spouses are living can reduce the future RMD burden for the survivor. Refining your lifetime income strategy today ensures that a surviving spouse is not left with a Medicare premium surcharge that erodes their long term financial security.
How Timing Impacts Your Tax Strategy and Medicare Costs
Managing the timing of large distributions is a pillar of a sophisticated tax-smart income strategy. If you are planning a significant expense, such as a major home renovation or the sale of an investment property in Gilbert, the date you realize those gains dictates your Medicare costs exactly two years later. Realizing a large capital gain in 2024 will directly influence your 2026 IRMAA brackets, potentially adding thousands to your annual healthcare overhead.
Retirees often face a choice between consolidating income into a single high-impact year or spreading it across multiple tax years. A single high-income year might trigger a top-tier surcharge for one twelve-month period, but it can clear the path for lower premiums in all subsequent years. In contrast, spreading a large withdrawal over three years to stay under a specific tax bracket could inadvertently keep you just above the IRMAA cliff for three consecutive years. This mistake often results in a higher total cost than simply taking the hit all at once.
Using a personalized retirement analysis helps determine which path is most efficient for your specific situation. By aligning the timing of capital gains and IRA distributions with your broader lifetime income strategy, you can navigate the 2026 Medicare surcharge cliffs with precision rather than reacting to them after the window for action has closed.